Insights That Add Up
Issue 12 · Blog Edition
BOOKKEEPING TIPS
What Is a Book Catch-up?
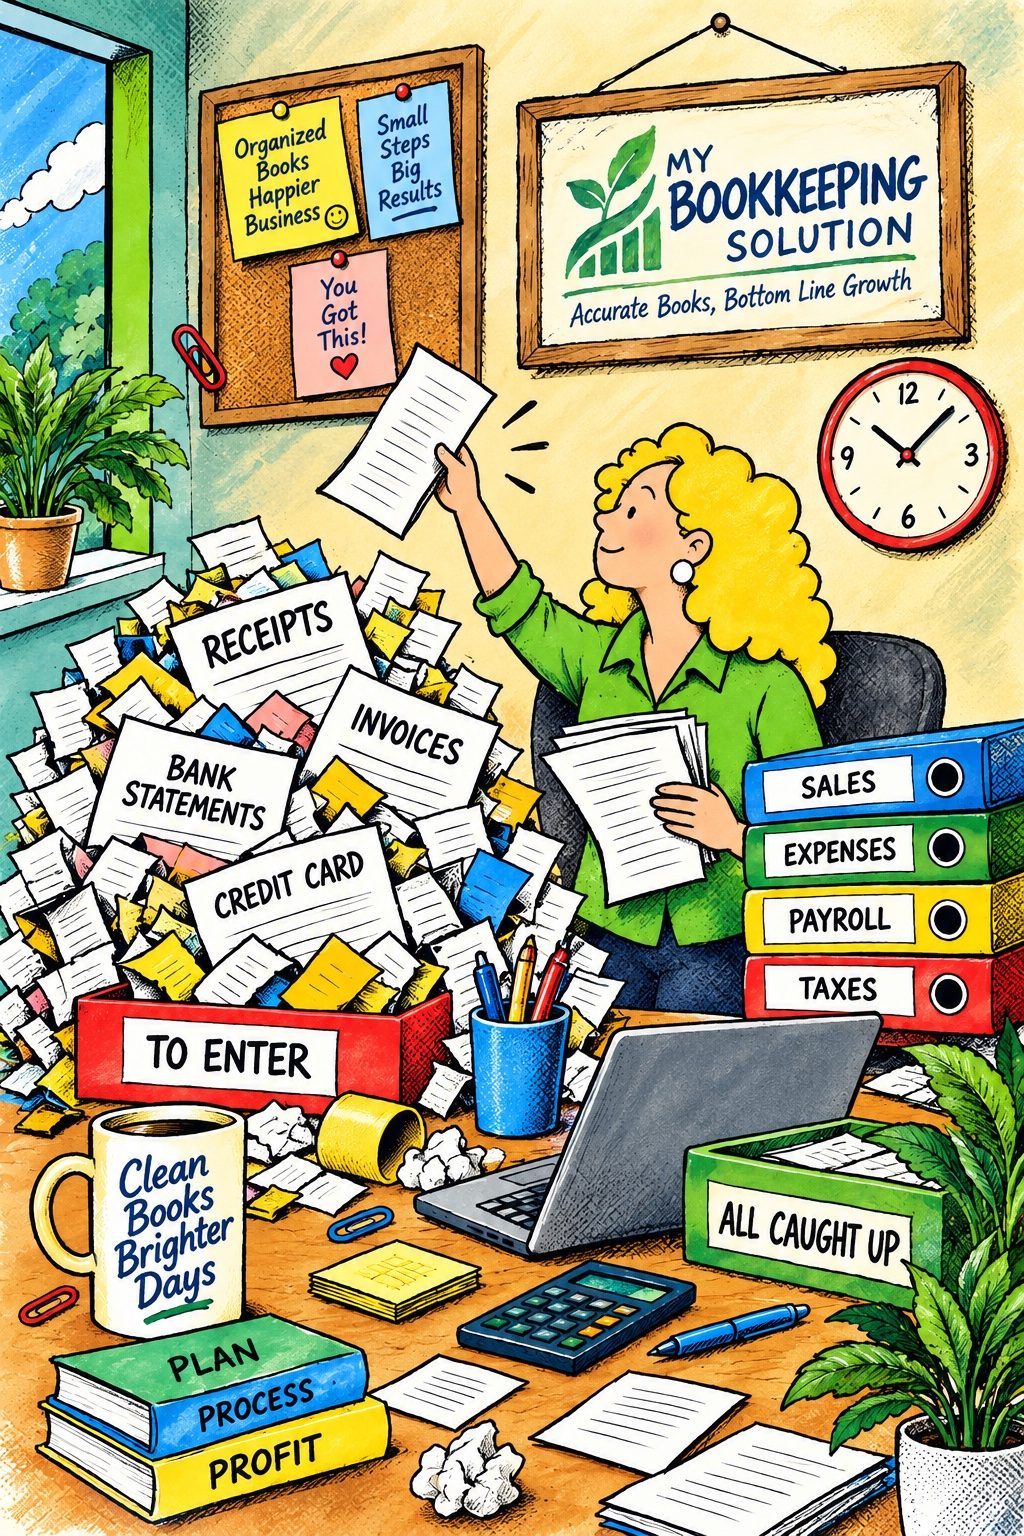
A book catch-up is an accounting process used to bring your financial records up to date when they have fallen behind. This is especially useful for small businesses that haven’t maintained their financial records regularly. Here’s what a typical book catch-up involves:
1. Gather Financial Documents
- Receipts and Invoices: Collect all receipts, invoices, and other financial documents. Make sure you have all the necessary paperwork for each transaction.
- Bank and Credit Card Statements: Gather all bank and credit card statements for the period you need to catch up on.
2. Organize Transactions
- Sort Documents: Sort your financial documents by date and type. This will help you systematically enter the data.
- Categorize Transactions: Categorize each transaction (e.g., sales, expenses, payroll) to ensure accurate accounting.
3. Enter Data into Accounting Software
- Backdate Entries: Enter all transactions into your accounting software, ensuring they are backdated correctly. This will help you maintain an accurate financial history.
- Reconcile Accounts: Reconcile your bank and credit card statements with the entries in your accounting software to ensure everything matches.
4. Review and Adjust Entries
- Check for Errors: Review the entries for any errors or discrepancies. Make corrections as needed.
- Adjust for Depreciation and Accruals: Ensure that any necessary adjustments for depreciation, prepaid expenses, and accruals are made.
Conducting a book catch-up helps you regain control over your business finances, ensures compliance with legal and tax obligations, and provides a clear picture of your financial health.
5. Update Financial Statements
- Income Statement: Generate an updated income statement to reflect your business’s revenue and expenses.
- Balance Sheet: Update your balance sheet to show the current state of your assets, liabilities, and equity.
- Cash Flow Statement: Create a cash flow statement to track the inflows and outflows of cash.
6. Tax Compliance
- Review Tax Records: Ensure that all tax-related transactions are accurately recorded.
- Prepare for Tax Filing: Get ready for tax season by making sure all your financial records are complete and accurate.
7. Set Up a Maintenance Plan
- Regular Updates: Create a plan to maintain your financial records regularly going forward. This can include weekly, monthly, or quarterly updates.
- Automate Where Possible: Consider using accounting software that automates data entry and reconciliation to save time and reduce errors.
© My Bookkeeping Solution · Cheryl Ledger